Executive Summary
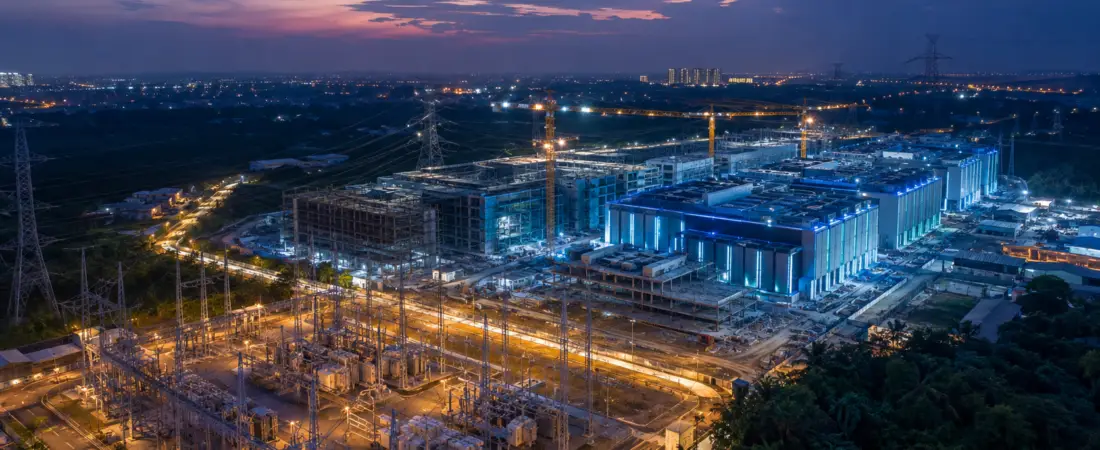
Asia-Pacific’s data-center development pipeline reached 26.455GW at the end of the first half of 2026, according to Cushman & Wakefield. Crucially, this is not operational or immediately available capacity: 4.764GW was under construction and 21.691GW was still planned.
The consultancy recorded 1.372GW of new operational capacity, yet regional colocation vacancy fell from 10.9% in H2 2025 to 10.3%. APAC is building rapidly, but pre-leasing and infrastructure constraints mean much of the future supply may be unavailable when it opens.
APAC Pipeline Expands
Cushman & Wakefield’s APAC Data Center H1 2026 Update covers 15 principal and secondary city markets, including Tokyo, Singapore, Sydney, Mumbai, Johor, Seoul, Jakarta and Bangkok. Its 26.455GW pipeline expanded by 7.103GW in six months.
The published H1 summary reports capacity in megawatts but does not define the 26.455GW as total facility electricity demand. It should therefore be treated as data-center market capacity not as an equivalent requirement from regional power grids.
Southeast Asia accounted for approximately half of APAC capacity under construction. Malaysia led with 1.039GW, followed by Thailand with 859MW. Johor alone had 602MW under construction and a 3.088GW development pipeline, while Sydney’s pipeline reached 2.134GW and Jakarta’s 1.699GW.
These categories matter. Announced or planned capacity may still depend on land, financing, planning approval, equipment and an executable grid connection. Under-construction capacity has progressed further, but it is neither operational nor necessarily available to a new customer.
AI Pre-Leasing Changes The Capacity Equation
Pre-leasing allows hyperscalers, neoclouds and AI infrastructure customers to reserve capacity before a building is completed. Cushman & Wakefield said in separate 2026 research that nearly all APAC capacity under construction had been pre-committed, although individual market conditions vary.
This explains why a large pipeline can coexist with low availability. A new facility may add operational megawatts when commissioned, yet contribute little or no capacity to the open colocation market because its halls and power allocation are already contracted.
AI is an important demand driver, but not the sole cause of tight supply. Cloud expansion, sovereign workloads and enterprise requirements continue to absorb capacity. AI deployments intensify the issue because customers may require large contiguous power blocks, higher rack densities and cooling systems that cannot be accommodated in every existing facility.
Power Becomes The Critical Constraint
Cushman & Wakefield describes the current phase as “power-constrained execution”. Pipeline capacity only becomes deliverable when utilities can provide the required connection, substations and transmission or distribution reinforcement.
Malaysia’s Tenaga Nasional established a Green Lane Pathway to reduce data-center connection delivery from a typical 36–48 months to 12 months. The initiative demonstrates both Johor’s development opportunity and the scale of coordination required between campuses and the grid.
Constraints differ by market. Singapore manages new development closely because of land, energy and sustainability considerations, while expansion in Johor is supported by larger campus sites but still depends on grid investment, water strategy and connectivity. A headline pipeline figure cannot capture these local delivery risks.
What It Means For Operators And Customers
Customers should procure against energized or contractually deliverable capacity, not market pipeline totals. Due diligence should establish the construction stage, committed occupancy, utility agreement, connection date, power density, cooling design and expansion rights.
For AI deployments, reserving megawatts is insufficient if the facility cannot support the required rack-level distribution and heat rejection. Buyers may need to engage earlier, consider multiple markets and negotiate phased delivery rather than wait for completed speculative space.
Developers, meanwhile, face a balance between securing anchor tenants and preserving capacity for a diversified customer base. Pre-leasing can support financing, but large commitments also concentrate delivery and counterparty risk.
What Happens Next
The leading indicators will be how much of the 21.691GW planned pipeline moves into construction, whether the 4.764GW being built reaches service on schedule, and how much remains uncommitted at delivery.
Utility connection awards, grid-investment programs and government sustainability rules will be as important as new campus announcements. Johor, Bangkok, Sydney, Mumbai and Jakarta merit particular attention because of their pipeline growth, but each presents a different combination of power, land, connectivity and regulatory conditions.
Conclusion
APAC does have a record development pipeline, but it does not have 26.5GW ready for occupation. More than four-fifths remains planned, while customers are reserving portions of the firmer pipeline before completion. For operators and buyers, the relevant measure is not announced scale but deliverable, powered and uncommitted capacity.
August 17, 2026 By: Joshua Anto